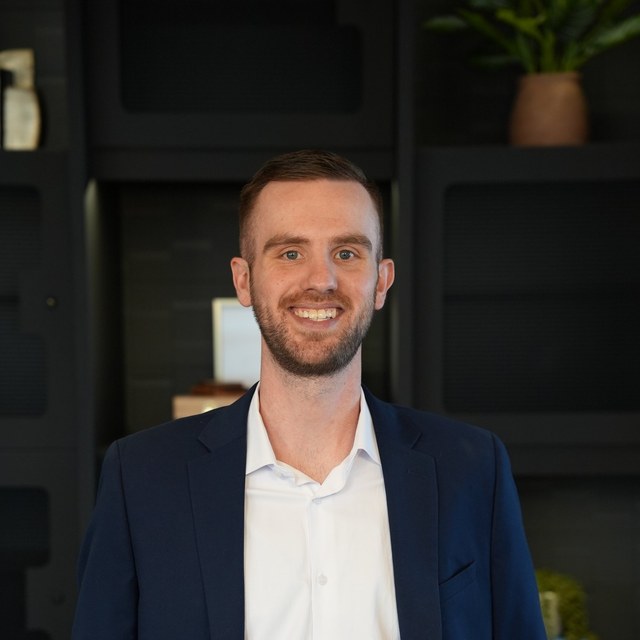
Available when houses actually sell
Showings at 7 PM, offer deadlines on Sunday, a "can we afford this one?" from the driveway — Jordan answers when the question happens, not Monday morning.
First-time buyers · Minnesota & Wisconsin
Buying your first home is a team sport. Your agent finds the house; Jordan De Jong makes the financing land — with straight answers on Saturday night, a payment on any listing in minutes, and a call to the listing agent with every offer.
Jordan · Loan Officer
usually replies in minutes
7
Days a week you can reach Jordan — nights and weekends included
10 min
For updated payment + cash-to-close math on offer day
1 call
To the listing agent with every offer you submit
1–2 days
Typical pre-approval turnaround once your documents are in*
* Timing varies by file and depends on receiving complete documentation. Turnaround figures are typical, not guaranteed. This is not an offer to enter into an agreement; not all customers will qualify. Rates, programs and terms are subject to change. All loans subject to credit and property approval.
Why "realtor-centric" matters
Houses sell on Saturday nights and offer deadlines land at 5 PM Sunday. If your financing can't keep pace with your agent, you lose houses you could have won. Jordan built his whole process around that one fact.
Showings at 7 PM, offer deadlines on Sunday, a "can we afford this one?" from the driveway — Jordan answers when the question happens, not Monday morning.
Seller credits, appraisal gaps, contingency language, closing dates — Jordan works through the money side with your agent so the offer is built right the first time.
A personal call vouching for your financing, with Jordan's cell number attached. It answers the one question every listing agent has: will this actually close?
How Jordan helps
Most buyers think a lender's job is a rate. The rate is table stakes. The job is everything that happens between "we like this house" and the keys — and doing it fast enough that you win the house.
Income, assets and credit actually reviewed — then a letter written to match your offer, not your max. Usually a day or two once your documents are in.
Text Jordan an address and a price. Principal, interest, taxes, insurance, mortgage insurance and cash to close come back in minutes.
Updated numbers, a matched letter, and a personal call to the listing agent with every offer you submit — the quiet advantage in a multiple-offer weekend.
Your agent finds the house. Jordan makes the financing land. They talk to each other, so you never play phone tag between them.
Minnesota Housing on this side of the river, WHEDA on the other. If assistance fits your file, Jordan pairs it with the right first mortgage.
Clear next steps at every milestone, straight answers to every question, and a process that runs quietly in the background until the keys.
The question everyone actually has
Not the loan payment — the whole payment. Principal, interest, property taxes, homeowners insurance, mortgage insurance, HOA if there is one. The calculator shows all of it, instantly, with no sign-up. Then text Jordan the address for numbers specific to that house.
Run my numbers →Jordan · Loan Officer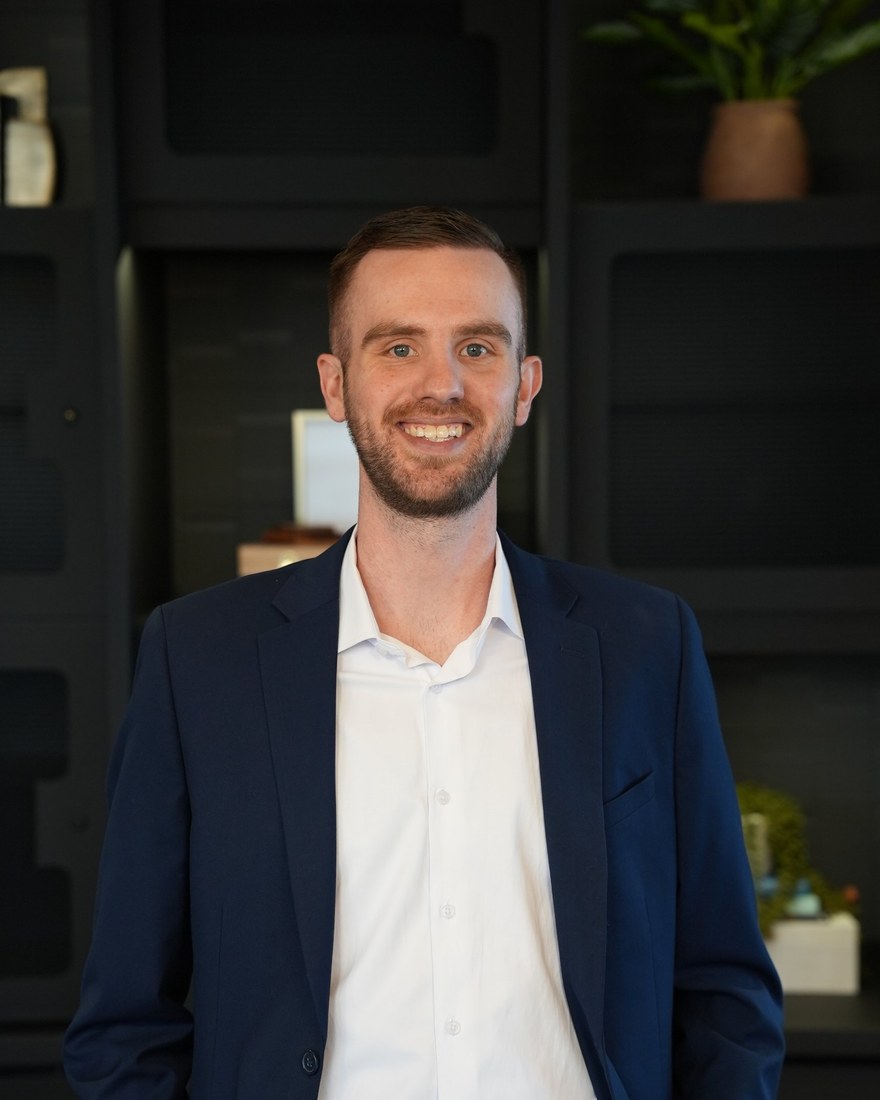
Meet Jordan
Jordan De Jong started originating loans at the hardest possible moment — right as rates ran up and every first closing felt like a cliffhanger. It taught him the thing he builds everything around now: set expectations early, communicate at every milestone, and prevent problems instead of managing them.
Loan Officer with Fairway Home Mortgage in Eden Prairie, licensed in Minnesota and Wisconsin, Winona State alum, and the lender your real estate agent wants on the team.
First-time buyer guides
The single most expensive myth in home buying — and what buyers in Minnesota and Wisconsin actually put down.
4 min read →02Price is only one lever. Here is what listing agents actually weigh — and how your lender can tip the scale.
6 min read →03Gift funds, assistance programs, seller credits and the real cash-to-close number nobody explains.
5 min read →Loan programs
The workhorse of home financing — flexible terms, competitive costs, and down payments as low as 3% for first-time buyers.
Learn more →The first-time buyer favorite — 3.5% down, friendlier credit requirements, and forgiving guidelines for real-life finances.
Learn more →For those who served — $0 down, no monthly mortgage insurance, and some of the strongest terms in all of lending.
Learn more →$0 down for homes in eligible smaller communities — many Twin Cities exurbs qualify, and most buyers have no idea.
Learn more →Financing above conforming loan limits for higher-priced homes — with the same guidance and straight answers.
Learn more →Minnesota and Wisconsin both have real down payment help — Minnesota Housing and WHEDA programs can put thousands toward your down payment and closing costs.
Learn more →Lower the payment, drop mortgage insurance, tap equity, or shorten the term — when the math works, Jordan will show you. When it doesn’t, he’ll tell you.
Learn more →Perfect. That is a ten-minute conversation, not homework. Text Jordan what you are wondering about.
Text 763-657-9279 →Ready when you are
No dumb questions, no pressure, no forms to fill out. Text Jordan what you are wondering about and get a straight answer — usually the same day, nights and weekends included.
Applications happen on Fairway's secure site — never here.